
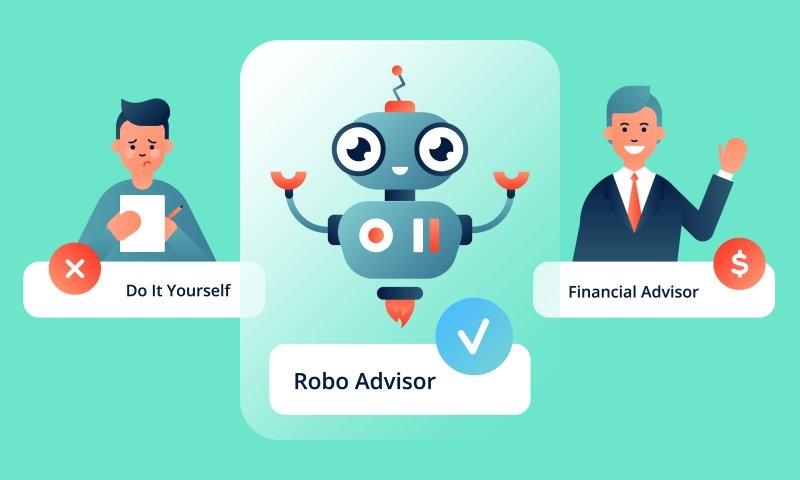
Nowadays, choosing how to handle one’s investments is not simply a case of either having a professional do things or doing it all by oneself. The third way is offered by the robo-advisor, an automated investment tool that will take care of building and managing the portfolio for its owner. On the other hand, a financial advisor has a lot to offer as well.
Robo advisor vs financial advisor: which one is better? It is up to your personal needs, financial complexity, level of involvement, and willingness to pay.
The robo advisor is an electronic investment service that gathers relevant data related to your goals, investment horizon, income, assets, and risk tolerance from an online questionnaire. This data is fed to an algorithm, which helps it create and maintain a portfolio.
Depending on the particular robo service, the following features such as rebalancing, tax loss harvesting, goal setting, and recurring investments may be available. Features may differ, and therefore, it is important for investors to know them by reading the service agreement.
The Securities and Exchange Commission defines the robo advisor as an automated digital investment advisory program and indicates that these programs aim to offer investment advice at cheaper rates than traditional investment advisory programs.
Financial advisors, on the contrary, offer financial advice in person. There is significant variation in the scope of services offered by financial advisors, since some of them are solely focused on managing your investment portfolio and others help with comprehensive financial planning of all aspects of your finances.
This distinction is important because the labels themselves do not tell you everything about the service. Before hiring an advisor, investors should understand what services are provided, how the professional is compensated, and whether there are conflicts of interest.
This distinction lies mainly in the way decisions are communicated and in how personalized they are.
With a robo advisor, the process of investing is mostly automated. The user submits his/her information, and the system uses its pre-programmed methodology in order to make the portfolio and sustain it. Such an approach can help cut down the effort of the investor.
In contrast, a financial advisor can maintain a more interactive process. An advisor can ask questions that go beyond questionnaire responses, and he can modify his recommendations, taking into account the information that is hard to get through automation.
Furthermore, this distinction goes beyond investment decisions. While the robo advisor concentrates on portfolio management, a human advisor coordinates several financial decisions at once.
Nevertheless, it should be mentioned that neither method automatically delivers better results when it comes to investing. Portfolio efficiency depends on asset allocation, costs, market situation, taxes, behavior, and the time horizon of the investor. More relevant to consider is how well the service fits the real investor's needs.
While the difference between the two models is noticeable in terms of cost, the latter should not be analyzed alone.
Fees for robo advisors could be taken as a percentage of the assets or in another way, depending on the company offering the service. There are some companies where account minimums are quite small, along with advisory fees. However, it is recommended that the underlying expense ratio, along with other fees, be considered by investors.
The Securities and Exchange Commission states that if advisory fees are small, the total cost is not automatically small. Investment expenses and other fees will add up to the cost of the automated investment portfolio.
The financial advisor's fees may also differ from each other. They could be taken in percentage form, a flat fee, an hourly fee, as well as a subscription or commission, among others. The proper comparison would depend on what services are included.
For instance, higher fees for an advisor could be more reasonable if the service includes comprehensive planning, tax planning, retirement planning, and regular meetings. On the other hand, high fees for extensive planning would not be very helpful for someone who is looking for an automatically diversified portfolio.
According to the SEC, asset-based fees charged by advisors are usually calculated on an annual percentage of assets basis; however, advisors can also charge other kinds of fees such as hourly or fixed.
When one is a beginner, the most important thing isn’t necessarily which service is better, but rather how much help he or she really needs.
If the person is financially simple, has a long-term view on investments, and plans to invest at regular intervals of time, automated investing could be more appealing, as the program would take care of portfolio construction and maintenance without the investor having to research each security or rebalance the portfolio himself or herself.
The main problem here would be to know what the program does and doesn’t do. The fact is that automated investing doesn’t take care of all investment risks, and an algorithm can’t make all financial decisions for you.
A beginner with many different financial priorities might benefit from human advice. A person who deals with debts, saving for a house, analyzing his or her insurance, and planning for retirement might have more complex questions than portfolio management.
It is important not to pay for things you don’t need, but also not to solve the problem with too limited an approach.
Both approaches have practical advantages and limitations.
Robo-advisor benefits include convenience, automation, and the potential for reduced cost of advisory services. The onboarding process is done mostly online, and investors receive a portfolio that is in line with their risk tolerance and objectives.
Automation can help avoid the tendency to constantly react emotionally with respect to investments. Systematic rebalancing and periodic investments do not require any effort on the part of the investor.
These qualities of a robo-advisor can prove useful to an investor who wants an investment process to be relatively easy and hassle-free.
There are limitations to the use of automation in financial advisory services. In most cases, a robo platform acts based on the information and rules provided within the system. It might not be able to conduct a complex discussion of personal family situations, business interests, inheritance problems, or conflicting financial goals.
Availability of human interaction varies among different robo platforms.
Some of the important advantages associated with financial advisors are personalization and broader thinking.
For instance, the advisor may assist his/her clients with analyzing their income requirements during the retirement period, incorporating tax-related issues in investment decisions, assessing insurance requirements, or even changing things after a major life event.
Interaction with a human being may be useful for those investors who are confused and/or want to make big changes under market conditions.
One of the disadvantages is the increased cost or complexity associated with it. Some relationships between the investor and the advisor may require higher minimum investments or ongoing costs. The investor also has to assess the advisor carefully since they differ in terms of experience, credentials, approach, services, and compensation.
The investor needs to know exactly what an advisor gets paid for before engaging in the relationship with him/her.
Also Check: Personal Finance Integration: Integrating Investment Apps
It makes more sense to use a robo-advisor if portfolio management is your main priority, and you are looking for an automated solution.
In addition, a robo-advisor may be helpful in the case if one wishes to create a habit of consistent investment without wasting much time on allocation and rebalancing.
On the other hand, a human advisor becomes more applicable if financial decisions start overlapping.
Consider getting personalized advice if you are close to retirement age, have a large number of taxable assets, run a company, are handling an inheritance, have complicated tax issues, and want to coordinate different financial objectives.
There is an alternative, too. Certain companies provide hybrid solutions that unite automated portfolio management with access to human experts. It is more interactive than a full-fledged advisory service but less interactive than robo-advisory.
The SEC mentions that the level of human interaction differs for various robo-advisors.
Before setting up an account, consider the actual services provided rather than relying on their marketing description.
Questions to ask include:
Fees need special consideration since even relatively modest periodic expenses could impact investment results over time. According to the SEC, you need to review both the advisory fee charged directly and the investment-related fee indirectly.
You must check the background of the human advisor or advisory firm before working with them. Investor.gov offers a tool to find out more about investment professionals and firms, what they do, fees, and their discipline.
This choice will be even more apparent if you begin with yourself rather than the technology.
If you seek an easy way to invest, are okay with making wider financial choices on your own, and just require portfolio management, then the automated route might be the answer.
If you are looking for an adviser who can help to align your investments with your retirement, tax, insurance, estate, or life planning, then the advisory relationship can offer you more comprehensive assistance.
Moreover, you have the possibility to make the choice anew at some point later in time. Starting off with automated investing today doesn’t mean that in the future you can’t work with a professional. Also, collaborating with a professional adviser doesn’t imply that you can’t automate things as well.
You should choose a model of service that corresponds to the complexity of your finances. You should compare the investment model, the range of support, fees, and services.
The better option would depend on your needs. Robo-advisors would be ideal for investors who mainly require automated investment management, while financial advisors would be ideal where general financial planning is important.
Identify your needs first - whether you only require investment management or assistance with several financial decisions. Consider the following aspects: services, human assistance, investment approach, cost, and minimum account size.
Consider the service offerings, investment approach, overall costs, minimum balances required, availability of human assistance, potential conflicts of interest, and how the firm gets paid. In the case of a human advisor, be sure to check out his credentials before forging ahead with the arrangement.
A robo-advisor can replace the role of the financial advisor in terms of creating a portfolio, rebalancing, and periodic investments, but it will not be able to do what a human advisor does in financial planning and other personal considerations.
Firstly, identify the types of financial decisions that you require assistance with. Next, compare the approach to investing, service features, human assistance, minimums, and costs involved for each one. In addition, take into account whether your finances will become increasingly complicated as your income and goals change.
This content was created by AI